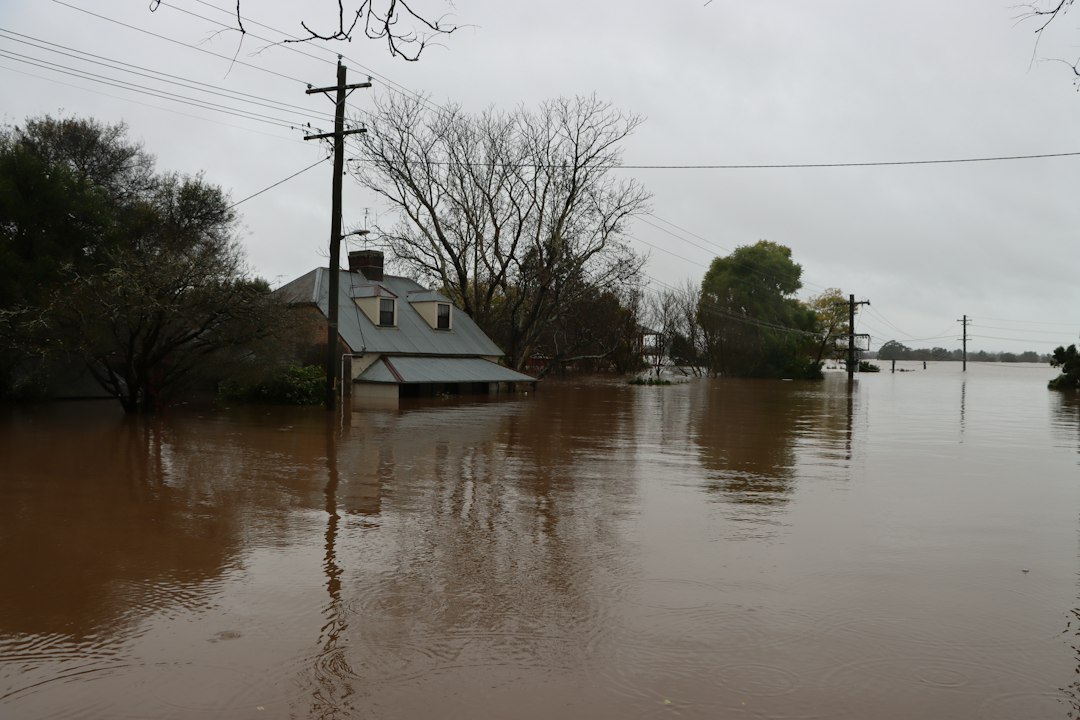
No. Standard homeowners and renters policies generally exclude flood damage, so you need a separate flood insurance policy. You can buy one through FEMA's National Flood Insurance Program (NFIP), which offers up to $250,000 for a home's structure and $100,000 for contents, or from a private insurer. NFIP coverage usually starts after a 30-day waiting period, so buy before storm season.
Does Homeowners Insurance Cover Floods? Why Flood Insurance Matters
In most cases, no. Standard homeowners policies in the US generally exclude damage from flooding. A homeowners policy usually covers sudden water damage that starts inside the home, such as a burst pipe, and it typically covers wind and hail. Rising water from heavy rain, overflowing rivers, storm surge or snowmelt is a different story. That is flood damage, and it normally needs its own policy.
According to FEMA, rain that enters through an opening created by wind, such as a torn-off section of roof, is generally treated as windstorm damage, which a homeowners policy may cover. Water that rises from the ground and flows into the house is flood damage, which a flood policy covers.
Where You Can Buy Flood Insurance
Americans have two main options: the National Flood Insurance Program (NFIP) and private flood insurance.
NFIP flood insurance
The NFIP is a federal program managed by FEMA. You usually do not buy it from the government directly. Most NFIP policies are sold and serviced by participating insurance companies and agents, so your current home or auto agent may be able to quote one. It is available in participating communities.
Private flood insurance
Private insurers also sell flood coverage. Depending on the company, a private policy may offer higher limits than the NFIP, coverage for additional living expenses while your home is repaired, a shorter waiting period, or broader basement coverage. Features and prices vary widely. Before switching from an NFIP policy, ask how a later return to the NFIP would be priced, and confirm that your mortgage lender will accept the private policy.
| Feature | NFIP | Private flood |
|---|---|---|
| Building coverage (single-family home) | Up to $250,000 | Varies; can be higher |
| Contents coverage | Up to $100,000 | Varies by insurer |
| Typical waiting period | 30 days, with some exceptions | Often shorter; varies |
| Temporary housing costs | Not included | Sometimes available |
| Basement contents | Very limited | Varies by policy |
The 30-Day Waiting Period
An NFIP policy generally takes effect 30 days after you apply and pay the premium. That means you cannot wait until a storm is in the forecast and expect to be covered. FEMA lists a few exceptions. There is generally no waiting period when the policy is required in connection with making, increasing, extending or renewing a mortgage, as long as you apply and pay at or before closing. A one-day wait can apply if you buy within a year after your community’s flood map is revised. A policy also will not cover a flood that is already in progress when you buy it.
Flood Zones and FEMA Maps
FEMA publishes flood maps that show the flood risk for each area. You can look up your address for free through FEMA’s Flood Map Service Center or ask your local floodplain office or insurance agent for help.
- High-risk areas are called Special Flood Hazard Areas and appear on maps as zones starting with A or V. FEMA describes these areas as having at least a 1 in 4 chance of flooding during a 30-year mortgage.
- Moderate- to low-risk areas appear as zones B, C or X. Flood insurance is not federally required there, but FEMA recommends it for all owners and renters.
If you own a home in a high-risk zone and your mortgage comes from a federally regulated or insured lender, you are generally required to carry flood insurance. Outside those zones, it is your choice. Keep in mind that, according to FEMA, properties in moderate- to low-risk areas account for more than 20 percent of NFIP claims. A low-risk label does not mean no risk.
What Flood Insurance Covers: Building vs. Contents
NFIP coverage is split into two parts, and you choose limits for each one separately.
Building coverage
This covers the structure and its built-in systems. Examples include the foundation, electrical and plumbing systems, furnaces, water heaters and built-in appliances. For a single-family home, the NFIP limit is up to $250,000.
Contents coverage
This covers your personal belongings, such as furniture, clothing, electronics and portable appliances. The NFIP limit for residential contents is up to $100,000. Contents coverage is not automatic. If you buy only building coverage, your belongings are not protected, so ask for both.
Basement Coverage Limits
Basements are where many flood policies disappoint people. Under the NFIP, a basement is any area with a floor below ground level on all sides. In that space, coverage is limited mostly to cleanup and to equipment that services the building, such as furnaces, water heaters, pumps and utility connections. Finished walls, floors and ceilings in a basement, and most belongings stored there, are generally not covered. If you have a finished basement, ask your agent exactly what would and would not be paid, or compare private options that may offer broader terms.
Do Renters Need Flood Insurance?
Renters often assume the landlord’s insurance will cover everything. It usually covers only the building, not your things. A typical renters policy, like a homeowners policy, generally excludes flood. Renters can buy NFIP contents coverage, up to $100,000, to protect their belongings.
How to Decide If You Need It
- Look up your flood zone on FEMA’s map and ask neighbors or your local office about past flooding.
- Consider how much you could afford to repair or replace on your own. Federal disaster aid, when available, is often limited and may come as a loan.
- Get quotes from both an NFIP agent and private insurers, and compare limits, waiting periods and basement terms.
- Buy well before storm season so the waiting period has passed when you need coverage.
Rules, pricing and available options vary by state, community and insurer, so confirm the details for your address before you buy.
Bottom Line
Homeowners and renters policies generally do not cover flooding, so if water could reach your home, a separate flood policy is the only real protection. The NFIP offers up to $250,000 for a home’s structure and up to $100,000 for contents, usually after a 30-day wait. Private flood insurance may offer more. Check your flood zone, compare quotes, and buy before you need it.
Frequently asked questions
Is flood insurance required by law?
Not for everyone. If your home is in a high-risk flood zone and your mortgage comes from a federally regulated or insured lender, you are generally required to carry it. Elsewhere it is optional, though lenders can still require it and FEMA recommends it for all property owners and renters.
Can I buy flood insurance right before a hurricane?
You can buy it, but it likely will not help with that storm. NFIP policies generally take effect 30 days after you apply and pay, with limited exceptions such as policies bought at a mortgage closing. Policies also do not cover a flood already in progress when you buy.
Does flood insurance cover my finished basement?
Only partly. NFIP policies cover basement cleanup and essential equipment such as furnaces, water heaters and pumps, but generally not finished walls, floors, ceilings or most belongings stored there. Some private flood policies offer broader basement coverage, so compare terms if this matters to you.
Read also
You may also search for: home insurance, coverage limits, insurance waiting periods
This article is for general information only and is not insurance, legal, tax or medical advice. Rules, coverage and prices vary by state, plan and insurer. Check your policy documents and speak with a licensed agent before making decisions.


